
Lenox House shares practical, down-to-earth guidance on british period property renovation and interiors for readers across the UK.
- 0123456789
- Angle Bd Abdelmoumen & rue soumaya, Résidence
- [email protected]
Lenox House shares practical, down-to-earth guidance on british period property renovation and interiors for readers across the UK.
 By Charlotte Pemberton
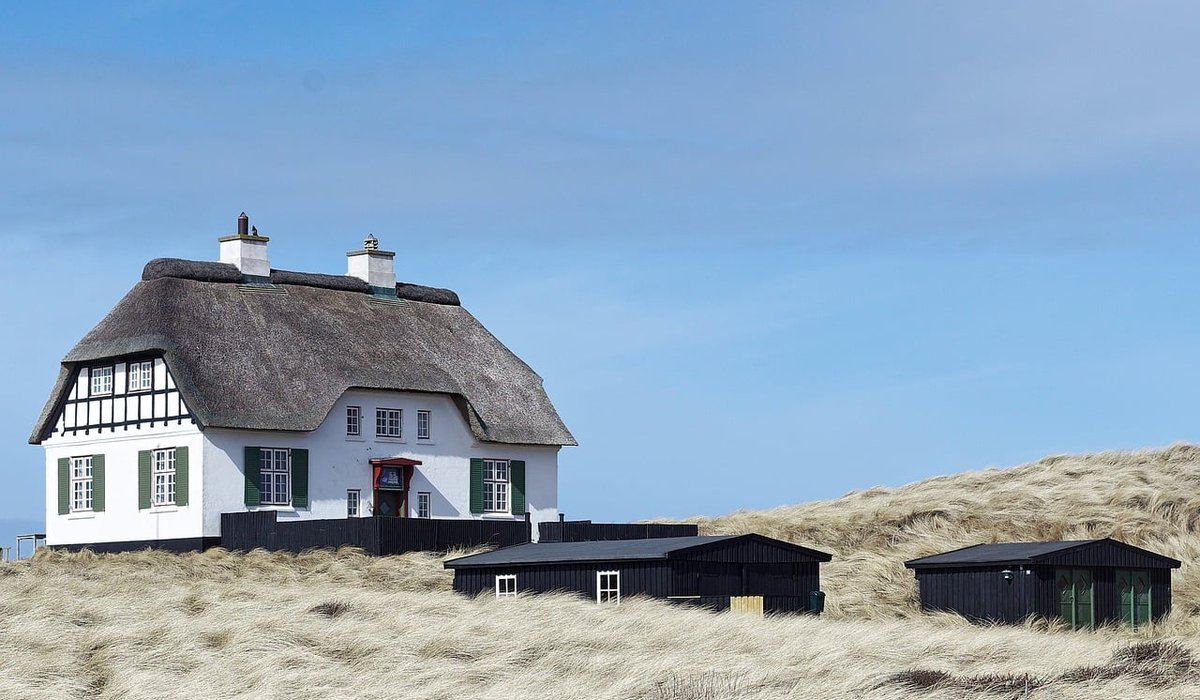
Listed buildings are graded to reflect their relative importance. Grade I covers buildings of exceptional interest, Grade II* buildings are particularly important, and Grade II are of special interest. Most listed homes fall into Grade II, but the grade does not change the basic rule: any work that affects the building’s character as a building of special architectural or historic interest needs listed building consent. Crucially, listing usually covers the whole building, inside and out, and can extend to curtilage structures such as garden walls, railings, outbuildings, and even some modern additions. Before you fall in love with a property, confirm exactly what is protected.
The official list entry is your starting point, but it is not a full inventory. It describes the features that justified listing, which might include a staircase, fireplaces, panelling, roof structure, or historic windows. If the description mentions something that is missing or badly altered, that is a red flag. It may also mean you will be expected to restore it. Check the map that accompanies the entry to see the curtilage boundary, and look for any references to later alterations that are now considered significant. A brief description does not mean only those features are protected.
Listed building consent is separate from planning permission, and you may need both. Consent is required for alterations that affect the building’s special interest, including many internal changes. Replacing windows, changing roof materials, removing internal walls or fireplaces, adding insulation or solar panels, and even painting or rendering external walls can all require consent. Carrying out unauthorised works can lead to enforcement action, fines, and an order to reinstate the original features. Always check whether previous owners obtained consent for past works, and ask your solicitor to check for any enforcement notices or Article 4 directions.
Standard builders and modern materials are often unsuitable for historic buildings. Cement mortar, plastic paints, and uPVC windows can trap moisture and cause long-term damage. You will need to budget for lime mortar, breathable paints, natural slate or stone, lead, cast iron, and traditional timber. Specialist tradespeople are in demand, so expect higher costs and longer waits. As a rule, add at least 20–25% contingency to your renovation budget, and get detailed quotes from contractors who have worked on listed buildings before. Cheaper options can end up costing far more when they fail.
Standard home insurance may not provide adequate cover for a listed building. You will likely need a specialist policy that recognises non-standard construction and historic features. Make sure the rebuild cost is accurate – not just the market value – and include outbuildings, boundary walls, and any unusual materials. Check that the policy covers accidental damage, escape of water, and alternative accommodation if the property becomes uninhabitable. Ongoing maintenance is also more intensive: gutters need clearing, roofs need checking, and ventilation must be managed to prevent damp. Budget around 1% of the property’s value each year for maintenance.
A mortgage valuation is not enough. Commission a full building survey from a surveyor who specialises in historic buildings. If you spot cracks or movement, instruct a structural engineer. A damp and timber survey is also wise, as historic buildings manage moisture differently from modern ones. Before you exchange contracts, speak to the local authority conservation officer – they can tell you what is likely to be approved and what is not. Finally, ask your solicitor to check covenants, rights of way, and boundary responsibilities. Buying a listed building is a privilege, but it comes with responsibilities. With the right checks, it can also be a deeply rewarding project.


We are not gonna make spamming
